Horizontal Inequality in Optimal Taxation: Evidence from a Development Context
Job Market Paper
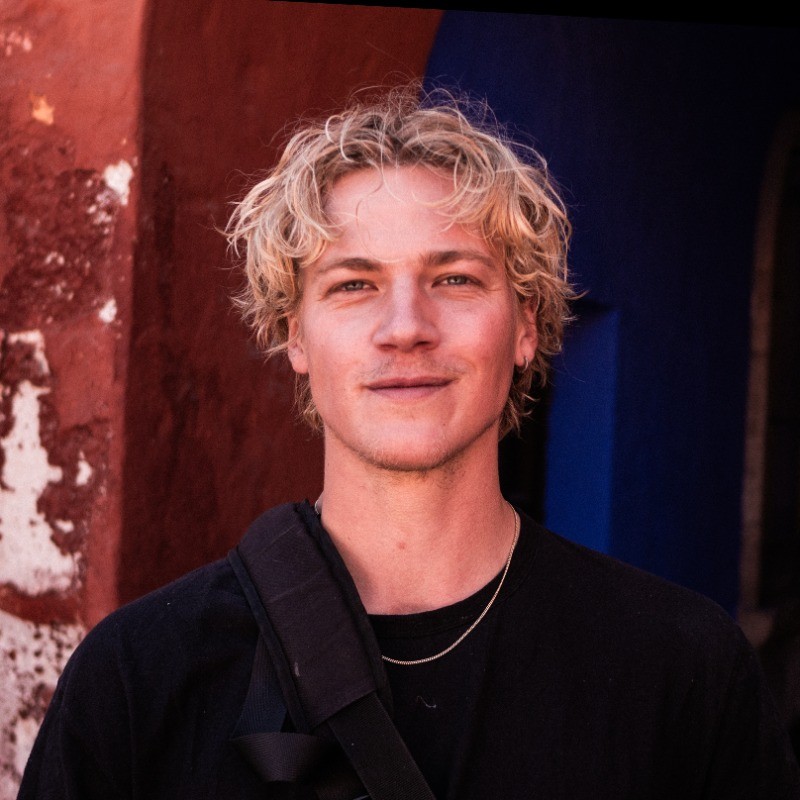
Magnus Eldrup
PhD Candidate in Economics · University of Copenhagen
Email: mel@econ.ku.dk
Affiliation: University of Copenhagen
Fields: Public economics, development, taxation
CV: PDF
Hi there. I am a PhD student at the University of Copenhagen with the Development Economics Research Group (DERG). Through my research I try to help better understand issues of taxation in developing countries, especially as it pertains to the interplay between the formal and the informal sector.
Before embarking on my PhD I completed the Msc. in Economics for Development at the University of Oxford and an MA. in Economics from the University of Copenhagen. In the fall of 2025 I visited the Harvard Kennedy School as a PhD Fellow.
Job Market Paper
Other Ongoing Research
Optimal Enforcement of Redistributive Taxation
with Claus Thustrup Kreiner
Tax Administration and VAT Neutrality: Theory and Evidence from Kenya
with Cyrus Mutuku and Bjørn Bo Sørensen
Abstract (click to expand)
Production efficiency is a central rationale for the VAT, but it is unclear whether it can be preserved when firms produce outputs subject to different tax treatment. We study this question through a 2019 reform of Kenya’s VAT refund apportionment formula using linked administrative tax and refund data. A one percentage point reduction in the marginal wedge induced firms to reorient production sharply toward zero-rated output, increasing zero-rated sales and total sales by about 5 percent of pre-reform sales and raising employment by 2–4 percent. Aggregating these estimates implies an increase in covered firms’ exports equivalent to roughly 3 percent of Kenya’s total goods exports. We develop a model that formalizes these distortions and shows they are inherent: source-based refund formulas cannot, in general, simultaneously preserve profit neutrality and marginal incentives when input use is unobserved. Our new database covering 182 countries shows that such source-based systems are the dominant global refund architecture, covering roughly two-thirds of the population living in countries with a VAT.A Worker’s Worth
with Paolo Falco and Andreas Menzel
Can AI Predict Top Five? Gender Bias in LLM Forecasts of Academic Excellence
with Paolo Falco and Sarah Zaccagni
Policy Work
Reforming Excise Taxation on Alcohol Products in Kenya and Reforming Excise Taxation on Tobacco Products in Kenya
with Alex Oguso, James Ochieng’, Nathan Remcho & Hellen Chemnyongoi